2026 Social Security COLA: What a 3.2% Increase Means
Anúncios
The projected 3.2% Cost-of-Living Adjustment (COLA) for 2026 Social Security benefits is poised to significantly affect the financial outlook for millions of beneficiaries, directly influencing their purchasing power.
Anúncios
Understanding the 2026 Social Security Cost-of-Living Adjustment: What a 3.2% Increase Means for Beneficiaries is crucial for millions of Americans planning their financial futures. This anticipated adjustment directly impacts your purchasing power and overall financial well-being in the coming years.
Understanding the Cost-of-Living Adjustment (COLA)
The Social Security Cost-of-Living Adjustment, or COLA, is an annual increase in benefits designed to offset the effects of inflation. It ensures that the purchasing power of Social Security benefits doesn’t erode over time due to rising prices for goods and services. This adjustment is a vital component of financial security for retirees, disabled individuals, and survivors.
Anúncios
The Social Security Administration (SSA) typically announces the COLA for the upcoming year in October, based on inflation data from the third quarter. While 2026’s COLA is still a projection, understanding its mechanics is key to appreciating its impact. It’s not an arbitrary number but a reflection of economic realities.
How COLA is Calculated
The COLA is determined by the percentage increase in the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). Specifically, the average CPI-W for the third quarter (July, August, and September) of the current year is compared to the average CPI-W for the third quarter of the last year in which a COLA was payable. If there’s an increase, that percentage becomes the COLA. If there’s no increase, or a decrease, there is no COLA.
- CPI-W Focus: The specific index used, CPI-W, directly measures inflation for a demographic that largely includes Social Security beneficiaries.
- Third-Quarter Data: The July, August, and September inflation figures are critical in determining the final COLA percentage.
- No Negative COLA: By law, Social Security benefits cannot decrease due to a COLA calculation, even if the CPI-W declines.
In essence, COLA acts as a protective measure, striving to maintain the real value of Social Security benefits. A 3.2% projection for 2026 suggests that inflation has been a significant factor, necessitating a notable adjustment to support beneficiaries’ financial stability.
The Projected 3.2% Increase: What it Means for Your Wallet
A projected 3.2% increase in the 2026 Social Security COLA is more than just a number; it translates directly into higher monthly benefits for millions of Americans. This adjustment aims to help beneficiaries keep pace with the rising cost of living, from groceries to healthcare. While it may seem modest, even a small percentage increase can have a substantial cumulative effect over time.
For someone receiving an average Social Security benefit, a 3.2% bump could mean tens of dollars more each month. For those with higher benefits, the increase will be even more significant. This added income can be crucial for covering essential expenses, especially for those on fixed incomes where every dollar counts.
Impact on Average Benefits
Let’s consider an illustrative example. If the average monthly Social Security benefit for retired workers is, say, $1,900 in late 2025, a 3.2% increase would add approximately $60.80 to their monthly check, bringing it to $1,960.80. This extra amount, while not making anyone rich, can provide a much-needed buffer against inflation.
- Enhanced Purchasing Power: The primary goal is to ensure beneficiaries can afford the same goods and services despite price increases.
- Budgetary Relief: For many, this increase can alleviate some pressure on tight budgets, allowing for more flexibility in spending.
- Long-Term Stability: Consistent COLA adjustments help maintain the long-term financial viability of retirement plans.
It’s important to remember that the 3.2% is a projection, and the final figure will depend on the official CPI-W data released later in 2025. However, planning based on this estimate allows beneficiaries to anticipate and adjust their financial strategies accordingly, ensuring they are prepared for the changes ahead.
Historical Context: COLA Trends and Economic Factors
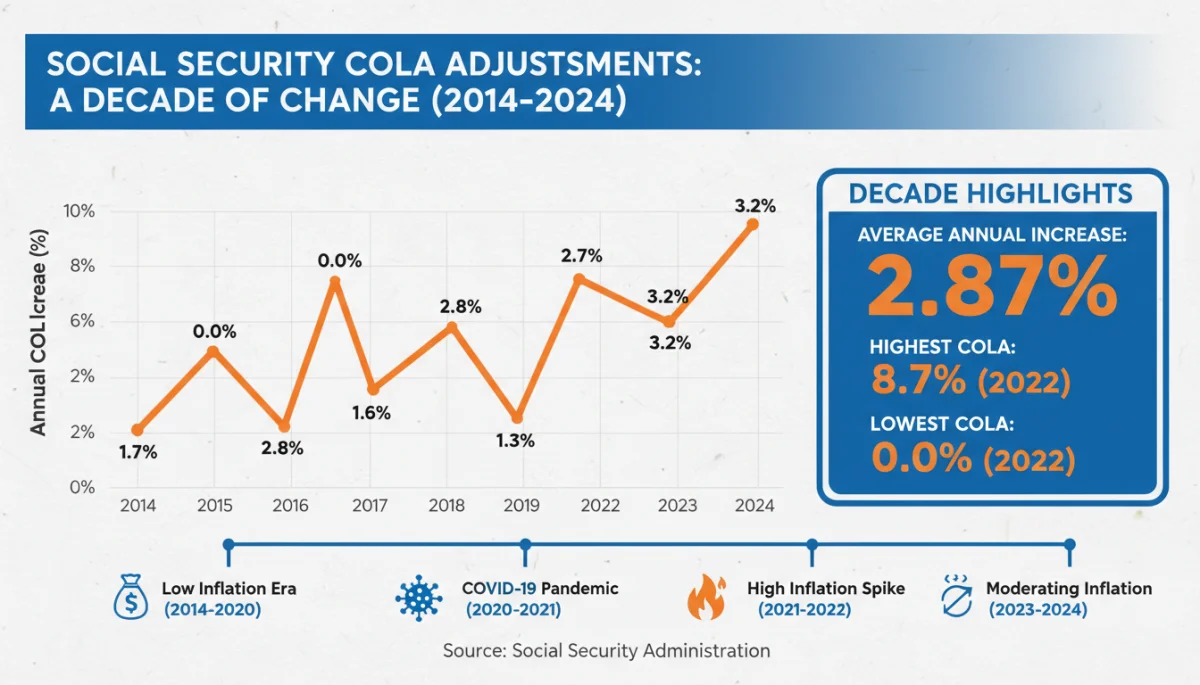
To fully appreciate the significance of a projected 3.2% COLA for 2026, it’s helpful to examine historical COLA trends and the economic factors that have influenced them. The COLA has varied significantly over the years, reflecting different periods of inflation and economic stability. Understanding this context provides valuable insight into what beneficiaries might expect.
For instance, recent years have seen some of the largest COLA increases in decades, driven by post-pandemic inflation surges. Prior to that, there were periods of very low or even zero COLA, particularly during times of economic recession or low inflation. These fluctuations underscore the direct link between the broader economy and Social Security benefits.
Key Economic Drivers of COLA
Several economic indicators play a crucial role in shaping the COLA. The most prominent is, of course, inflation, as measured by the CPI-W. However, other factors also contribute to the economic environment that drives inflation.
- Energy Prices: Fluctuations in oil and gas prices have a significant ripple effect on the cost of goods and services, directly impacting CPI-W.
- Supply Chain Disruptions: Global events affecting supply chains can lead to shortages and higher prices, pushing inflation upward.
- Wage Growth: Strong wage growth can contribute to increased consumer demand, potentially leading to higher prices.
- Monetary Policy: Decisions by the Federal Reserve regarding interest rates can influence the overall economic climate and inflation rates.
The 3.2% projection for 2026 suggests that while inflationary pressures may be easing compared to peak levels, they are still substantial enough to warrant a significant adjustment. This continuous balancing act between economic growth and price stability is what ultimately dictates the COLA each year.
Navigating the Changes: Financial Planning with the New COLA
The announcement of the 2026 Social Security COLA provides an opportune moment for beneficiaries to review and adjust their financial planning. While the increase is designed to maintain purchasing power, it’s essential to understand how it integrates into your overall financial strategy. Proactive planning can help maximize the benefit of this adjustment.
It’s not just about the increased income; it’s also about how that income interacts with other aspects of your financial life, such as taxes, Medicare premiums, and other retirement savings. A holistic view ensures that the COLA works in your favor and helps you meet your financial goals effectively.
Adjusting Your Budget and Spending
With a higher monthly benefit, reviewing your budget is a smart first step. Identify areas where the increased income can have the most impact. This might involve allocating more towards essential expenses, building an emergency fund, or even enjoying a few modest discretionary purchases.
- Re-evaluate Monthly Expenses: Update your budget to reflect the new income and current cost of living.
- Prioritize Savings: Consider directing a portion of the increase into savings or investments, if possible.
- Review Debt: Use any extra funds to pay down high-interest debt, improving your financial health.
Furthermore, understanding the timing of the increase is important. The new COLA typically takes effect with the December benefits, which are paid in January of the following year. This lag means you should plan for the current benefit level until the new year begins.
Potential Downsides and Unintended Consequences
While a COLA increase is generally positive, it’s important to acknowledge that there can be potential downsides and unintended consequences for some beneficiaries. These aspects often relate to how Social Security benefits interact with other income streams, tax thresholds, and specific government programs. A 3.2% increase, while beneficial, might trigger certain thresholds for some individuals.
One common concern is the potential for increased Medicare Part B premiums. While the Social Security Act generally protects beneficiaries from a reduction in their net Social Security benefit due to a Part B premium increase (the “hold harmless” provision), this protection doesn’t apply to everyone. Those new to Medicare or with higher incomes might see a larger portion of their COLA go towards increased premiums.
Impact on Other Benefits and Taxes
Another area of concern is how an increased Social Security benefit might affect eligibility for other low-income assistance programs. Many state and federal programs have income limits, and a higher Social Security payment could inadvertently push some beneficiaries over these thresholds, leading to a reduction or loss of other vital support.
- Increased Taxable Income: For some beneficiaries, a higher Social Security income could result in a larger portion of their benefits becoming taxable.
- Medicare Part B Premiums: Higher income levels can lead to Income-Related Monthly Adjustment Amounts (IRMAA) for Medicare Part B and D.
- Eligibility for Assistance Programs: Certain means-tested programs may see beneficiaries become ineligible due to the increased income.
It’s crucial for beneficiaries to consult with a financial advisor or tax professional to understand the specific implications of the 2026 COLA on their individual circumstances. Proactive analysis can help mitigate any unexpected negative impacts and ensure that the benefit increase truly enhances their financial well-being.
Future Outlook for Social Security and Beneficiaries
Looking beyond the 2026 COLA, the future outlook for Social Security and its beneficiaries remains a topic of ongoing discussion and importance. While annual COLA adjustments address short-term inflation, the long-term solvency of the Social Security trust funds is a broader concern. Understanding these larger trends is vital for comprehensive financial planning.
Projections from the Social Security Administration (SSA) indicate that the trust funds may only be able to pay a certain percentage of scheduled benefits in the coming decades without legislative changes. This doesn’t mean Social Security will disappear, but it highlights the need for ongoing policy discussions to ensure its continued strength for future generations of beneficiaries.
Factors Influencing Long-Term Solvency
Several demographic and economic factors contribute to the long-term financial health of Social Security. These include birth rates, life expectancy, and the overall economic growth of the nation.
- Demographic Shifts: A lower birth rate combined with increased life expectancy means fewer workers are contributing relative to the number of beneficiaries.
- Economic Growth: Robust economic growth leads to higher wages and more tax contributions, bolstering the trust funds.
- Policy Debates: Discussions around potential solutions, such as adjusting the full retirement age, modifying benefit formulas, or increasing the Social Security tax cap, are ongoing.
For current and future beneficiaries, staying informed about these developments is essential. While the 2026 COLA provides an immediate boost, a comprehensive approach to retirement planning involves considering the broader landscape of Social Security’s future. This proactive engagement allows individuals to make informed decisions and advocate for policies that support the program’s long-term viability.
| Key Aspect | Brief Description |
|---|---|
| Projected COLA | A 3.2% increase is projected for 2026 Social Security benefits, aimed at countering inflation. |
| Calculation Method | Based on the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W) from Q3. |
| Beneficiary Impact | Increased monthly benefits, enhancing purchasing power, but may affect other benefits or taxes. |
| Financial Planning | Opportunity to re-evaluate budgets, savings, and consult with financial advisors for personalized advice. |
Frequently Asked Questions About the 2026 COLA
The official 2026 COLA is typically announced by the Social Security Administration in October of 2025. This timing allows them to analyze the third-quarter inflation data, which is crucial for the final calculation. Beneficiaries should monitor SSA announcements for the precise figure.
No, the 3.2% is currently a projection based on available economic data and forecasts. The final COLA percentage will be determined by the actual Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W) for July, August, and September 2025. The official announcement will confirm the exact figure.
For most beneficiaries, the “hold harmless” provision prevents Medicare Part B premiums from reducing your net Social Security benefit. However, this doesn’t apply to everyone. If you’re new to Medicare, have higher income, or your premiums are paid directly, you might see an increase that offsets some of your COLA.
Yes, for some beneficiaries, a COLA increase can push their combined income (adjusted gross income plus half of Social Security benefits) over certain thresholds, making a portion of their Social Security benefits subject to federal income tax. It’s advisable to consult a tax professional.
The 2026 COLA increase will typically be applied to your Social Security benefits starting with the payments issued in January 2026. This means the higher amount will be reflected in your first payment received in the new calendar year, usually around the second or third Wednesday of January.
Conclusion
The projected 3.2% Cost-of-Living Adjustment for 2026 is a significant development for millions of Social Security beneficiaries, offering a crucial boost to their financial stability in the face of ongoing inflation. While the official announcement is still pending, understanding the mechanics of COLA, its historical context, and its potential impacts is vital for effective financial planning. Beneficiaries are encouraged to review their budgets, consider the implications for taxes and other benefits, and consult with financial professionals to ensure they maximize the positive effects of this adjustment. Proactive engagement with these changes will empower individuals to navigate their financial futures with greater confidence and security.