Fed Rate Hike: 0.25% Impact on US Homeowners
Anúncios
The Federal Reserve’s recent 0.25% interest rate hike directly impacts millions of US homeowners by increasing borrowing costs, affecting mortgage payments, and reshaping the broader housing market landscape.
The recent announcement by the Federal Reserve of a 0.25% interest rate hike marks a significant shift in the economic landscape, poised to impact millions of homeowners across the United States. This move, while seemingly minor, carries profound implications for household budgets, mortgage rates, and the broader housing market. Understanding these changes is crucial for anyone with a home loan or considering one.
Anúncios
Understanding the Federal Reserve’s Decision
The Federal Reserve, often referred to as the Fed, functions as the central bank of the United States. Its primary mandates include maximizing employment, stabilizing prices, and moderating long-term interest rates. When the Fed decides to raise interest rates, it typically signals a strategy to combat inflation and cool down an overheating economy. This particular 0.25% hike is a deliberate step in that direction, aimed at recalibrating economic forces.
The decision to adjust the federal funds rate, which is the target rate for overnight lending between banks, has a ripple effect throughout the financial system. Banks use this rate as a benchmark for their own lending practices, influencing everything from credit card APRs to auto loan interest. For homeowners, the most direct and often most substantial impact is felt in the mortgage market.
Anúncios
The Mechanism of Rate Hikes
When the Fed raises its benchmark rate, commercial banks face higher costs for borrowing money. These increased costs are then passed on to consumers in the form of higher interest rates on various loans. This mechanism is designed to slow down borrowing and spending, thereby reducing demand and, ideally, curbing inflationary pressures. The 0.25% increase, while modest, is part of a larger strategy.
- Inflation Control: The primary driver behind recent rate hikes has been persistent inflation, which erodes purchasing power.
- Economic Moderation: By making borrowing more expensive, the Fed aims to slow down economic activity to a sustainable pace.
- Market Expectations: These decisions are often anticipated by financial markets, but the actual announcement can still trigger significant adjustments.
The Fed’s communication surrounding these decisions is meticulously analyzed by economists, investors, and consumers alike. The language used by officials often provides clues about future monetary policy, allowing individuals and businesses to prepare for potential shifts. This transparency is crucial for maintaining market stability and public confidence in the Fed’s actions. The recent hike, therefore, is not an isolated event but a piece of a larger economic puzzle.
In conclusion, the Federal Reserve’s decision to raise interest rates by 0.25% is a strategic move designed to manage inflation and stabilize the economy. This action sets in motion a series of financial adjustments that will inevitably influence borrowing costs across the board, with particular relevance for the housing sector and current homeowners.
Direct Impact on Mortgage Payments
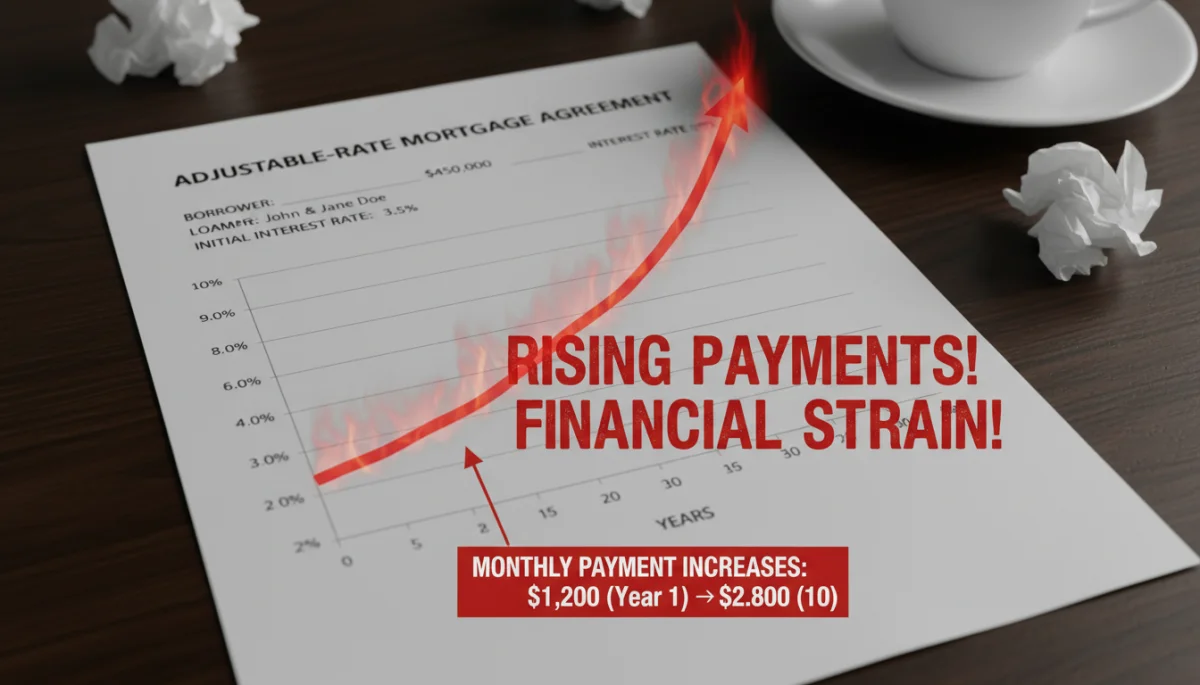
For millions of homeowners, the most immediate and tangible consequence of a rate hike is its effect on mortgage payments. While fixed-rate mortgages remain unchanged, those with adjustable-rate mortgages (ARMs) will likely see their monthly payments increase. This can significantly impact household budgets, especially for those already managing tight finances.
Adjustable-rate mortgages are designed to fluctuate with market interest rates. When the Fed raises its benchmark rate, the indexes to which ARMs are tied typically follow suit. This leads to an upward adjustment in the interest rate applied to the ARM, resulting in higher monthly payments for the homeowner. The timing and magnitude of these adjustments depend on the specific terms of each mortgage agreement, including the adjustment period and interest rate caps.
Understanding Adjustable-Rate Mortgages (ARMs)
ARMs usually start with a fixed interest rate for an initial period, typically 3, 5, 7, or 10 years. After this initial period, the rate adjusts periodically, often annually. These adjustments are tied to a specific financial index, such as the Secured Overnight Financing Rate (SOFR) or the Constant Maturity Treasury (CMT) rate. The Fed’s rate hike directly influences these underlying indexes.
- Initial Fixed Period: Homeowners enjoy a stable payment for a set number of years.
- Adjustment Period: After the initial period, rates can change, usually annually.
- Rate Caps: Most ARMs have caps that limit how much the interest rate can increase in a single adjustment period and over the life of the loan.
Even a seemingly small increase of 0.25% can translate into hundreds of dollars more per year for a substantial mortgage balance. For example, on a $300,000 ARM, a 0.25% increase could add around $50 to $75 to a monthly payment, depending on the remaining loan term and current rate. Over a year, this adds up to $600-$900, which can be a considerable burden for many families.
In summary, the Federal Reserve’s 0.25% rate hike directly impacts homeowners with adjustable-rate mortgages, leading to increased monthly payments. Understanding the terms of one’s ARM and preparing for potential payment adjustments is essential for financial stability in this changing interest rate environment.
Impact on Fixed-Rate Mortgages and Refinancing
While existing fixed-rate mortgages are immune to the immediate effects of the Fed’s rate hike, the overall mortgage market, including new fixed-rate loans, is significantly influenced. This means that individuals looking to purchase a new home or refinance an existing mortgage will face higher borrowing costs.
Fixed-rate mortgages are not directly tied to the federal funds rate. Instead, they are more closely correlated with the yield on U.S. Treasury bonds, particularly the 10-year Treasury note. However, the Fed’s monetary policy decisions, including rate hikes, indirectly affect Treasury yields as they signal the central bank’s stance on inflation and economic growth. When the Fed raises rates, it generally pushes up bond yields, which in turn leads to higher fixed mortgage rates.
Refinancing Becomes Less Attractive
For many homeowners, refinancing has been a popular strategy to lower monthly payments or tap into home equity. However, with rising interest rates, the attractiveness of refinancing diminishes significantly. The primary goal of refinancing is often to secure a lower interest rate than the current one. If new mortgage rates are higher, there is little incentive to refinance, unless it is to convert an ARM to a fixed-rate loan to avoid future payment increases.
- Higher Costs: New fixed-rate mortgages will come with higher interest rates, increasing the overall cost of homeownership for new buyers.
- Reduced Savings: Refinancing to lower payments becomes less feasible as market rates climb.
- Equity Access: Home equity loans and lines of credit (HELOCs) also see interest rate increases, making borrowing against home equity more expensive.
The impact on refinancing is not just about the interest rate. Closing costs associated with refinancing can be substantial, often ranging from 2% to 5% of the loan amount. When combined with a higher interest rate, these costs make refinancing a less financially viable option for many. Homeowners must carefully weigh the potential savings against these upfront expenses.
In conclusion, the Fed’s rate hike indirectly leads to higher fixed-rate mortgages, making home purchases more expensive and significantly reducing the appeal of refinancing for most homeowners. This shift necessitates careful financial planning for anyone considering a new mortgage or adjusting an existing one.
Broader Housing Market Implications
Beyond individual mortgage payments, the Federal Reserve’s interest rate hike sends ripples through the entire housing market. Higher borrowing costs tend to cool down demand, potentially leading to a moderation in home price appreciation and a shift in market dynamics from a seller’s to a more balanced or even buyer’s market.
When mortgage rates increase, the purchasing power of potential homebuyers decreases. A higher interest rate means that for the same monthly payment, a buyer can afford a smaller loan amount. This effectively prices some buyers out of the market or forces them to consider less expensive homes, thereby reducing the pool of eligible buyers and dampening overall demand. This reduction in demand can, over time, lead to slower home price growth or even price declines in some regions.
Affordability Challenges Intensify
Housing affordability has been a significant concern in recent years, with rapidly escalating home prices outpacing wage growth. The rate hike exacerbates this challenge, making homeownership even less accessible for first-time buyers and those with limited budgets. The dream of owning a home moves further out of reach for many as the cost of borrowing increases.
- Reduced Buyer Demand: Higher mortgage rates decrease affordability, leading to fewer active buyers in the market.
- Slower Price Growth: A decrease in demand typically results in a deceleration of home price appreciation, or even price corrections.
- Increased Inventory: As homes take longer to sell, the supply of available properties may increase, further impacting prices.
Furthermore, the rate hike can influence investor behavior in the housing market. Real estate investors often rely on borrowed capital, and higher interest rates make their investments less profitable. This could lead to a reduction in investor activity, particularly in speculative markets, further contributing to a cooling trend. The rental market could also see increased demand as more individuals are priced out of homeownership, potentially leading to higher rental prices.
In essence, the 0.25% interest rate hike is a significant factor in shaping the future trajectory of the housing market. It is likely to temper the heated conditions seen in recent years, leading to a more challenging environment for buyers and potentially a more balanced market for sellers, with affordability remaining a central issue.
Strategies for Homeowners to Adapt
In light of the Federal Reserve’s interest rate hike, homeowners, particularly those with adjustable-rate mortgages, need to consider proactive strategies to mitigate potential financial strain. Adapting to these changes can help maintain financial stability and make informed decisions about their housing situation.
One of the first steps for homeowners with ARMs is to thoroughly review their mortgage terms. Understanding when the next rate adjustment is scheduled, what index their mortgage is tied to, and what the rate caps are is crucial. This knowledge empowers homeowners to anticipate changes in their monthly payments and plan accordingly.
Financial Planning and Budget Adjustments
For those facing increased mortgage payments, re-evaluating the household budget becomes paramount. Identifying areas where expenses can be reduced or income can be increased is a practical approach. This might involve cutting discretionary spending, seeking additional income streams, or even exploring options for debt consolidation to reduce overall interest payments.
- Budget Review: Scrutinize monthly expenses to find areas for savings.
- Emergency Fund: Ensure an adequate emergency fund is in place to cover unexpected increases in payments.
- Debt Reduction: Prioritize paying down high-interest debts to free up cash flow.
Another strategy is to explore refinancing options, even if current rates are higher than before. While refinancing to a lower rate might be less likely, converting an ARM to a fixed-rate mortgage could provide payment stability and peace of mind, especially if future rate hikes are anticipated. Homeowners should consult with a financial advisor or mortgage professional to assess if this is a viable option for their specific situation, considering closing costs and the remaining term of their loan.
Moreover, some homeowners might consider making extra principal payments to reduce their loan balance, thereby mitigating the impact of future interest rate increases. Even small additional payments can significantly reduce the total interest paid over the life of the loan. Proactive engagement with their financial situation is key for homeowners navigating this new economic reality.
In conclusion, homeowners can adapt to the Fed’s rate hike by meticulously reviewing their mortgage terms, adjusting their budgets, and exploring refinancing or extra payment options. These proactive measures are vital for maintaining financial health in a rising interest rate environment.
Economic Outlook and Future Rate Movements
The Federal Reserve’s 0.25% interest rate hike is not an isolated event but part of a broader monetary policy strategy. Understanding the economic outlook and potential future rate movements is essential for homeowners and prospective buyers to make informed long-term financial decisions. The Fed’s actions are heavily influenced by economic data, particularly inflation and employment figures.
Current economic indicators suggest that while inflation may be showing signs of moderating, it remains above the Fed’s target of 2%. Additionally, the labor market has shown remarkable resilience, with low unemployment rates. These factors combined indicate that the Fed may continue its hawkish stance, potentially leading to further rate hikes in the coming months, albeit at a slower pace.
Factors Influencing Future Decisions
Several key economic indicators will guide the Federal Reserve’s future decisions regarding interest rates. These include the Consumer Price Index (CPI), which measures inflation, and the unemployment rate, which reflects the health of the labor market. Geopolitical events and global economic conditions also play a role in shaping the Fed’s policy choices.
- Inflation Trends: Sustained high inflation will likely prompt further rate increases.
- Employment Data: A strong labor market gives the Fed more room to raise rates without fear of causing a recession.
- Economic Growth: The overall pace of economic expansion influences the need for monetary tightening or easing.
Market analysts and economists generally anticipate that the Fed may implement one or two more modest rate hikes before pausing to assess the impact of its policies. However, this outlook is subject to change based on incoming economic data. Homeowners should stay informed about these developments, as they directly affect mortgage rates and the broader financial landscape. Preparing for a scenario where rates could continue to climb, even modestly, is a prudent approach.
The long-term goal of the Fed is to achieve a stable economic environment with controlled inflation and full employment. The current rate hike is a step towards that equilibrium. Understanding these underlying economic forces allows homeowners to better forecast future mortgage costs and plan their finances accordingly, ensuring they are not caught off guard by subsequent policy adjustments.
In conclusion, the Federal Reserve’s recent rate hike is part of an ongoing effort to stabilize the economy. Future rate movements will depend on evolving economic data, particularly inflation and employment, making it crucial for homeowners to monitor these trends and prepare for potential further adjustments in borrowing costs.
Navigating the Housing Market as a Buyer or Seller
For individuals contemplating buying or selling a home, the Federal Reserve’s 0.25% interest rate hike introduces new considerations. The shift in monetary policy impacts market dynamics, influencing both buyer affordability and seller expectations. Navigating this evolving landscape requires a strategic approach and a clear understanding of current market conditions.
Prospective buyers will find that higher mortgage rates reduce their purchasing power. This means they may need to adjust their budget, consider smaller homes, or look in less competitive neighborhoods. The urgency to buy might decrease as interest rates rise, leading to a more thoughtful and less frantic purchasing process compared to recent years. Buyers should focus on pre-approval to understand their exact borrowing capacity.
Considerations for Sellers
Sellers, on the other hand, may need to temper their expectations regarding home price appreciation and time on the market. With fewer eligible buyers and reduced purchasing power, homes might take longer to sell, and offers may be closer to the asking price, or even below, depending on the local market. The days of multiple, over-asking-price bids might become less common.
- Buyer’s Market Shift: Increased rates can tilt the market balance from sellers to buyers.
- Realistic Pricing: Sellers may need to price their homes more competitively to attract buyers.
- Market Patience: Both buyers and sellers may need to exercise more patience in the transaction process.
For sellers, preparing a home meticulously for sale, ensuring it is in excellent condition, and marketing it effectively become even more critical. Offering incentives or being flexible with terms might also become more common strategies to attract buyers in a less frenzied market. Understanding local market trends, which can vary significantly even within the same state, is paramount.
Buyers, meanwhile, might find new opportunities as competition eases. While borrowing costs are higher, a less competitive market could mean more negotiating power, fewer bidding wars, and a greater selection of homes. Focusing on long-term investment rather than short-term gains becomes even more important in this environment. Consulting with experienced real estate agents who understand the nuances of a changing market is invaluable for both parties.
In conclusion, the Fed’s rate hike reshapes the housing market for both buyers and sellers. Buyers face reduced affordability but potentially less competition, while sellers must adjust expectations and strategize for a more discerning market. Strategic planning and informed decision-making are key to success in this evolving landscape.
| Key Impact Area | Brief Description of Effect |
|---|---|
| Adjustable-Rate Mortgages (ARMs) | Monthly payments will likely increase, impacting household budgets. |
| Fixed-Rate Mortgages & Refinancing | New loans and refinancing become more expensive, reducing affordability. |
| Housing Market Demand | Higher rates typically cool demand, potentially slowing home price growth. |
| Homeowner Strategies | Reviewing terms, budgeting, and exploring refinancing or extra payments are key. |
Frequently Asked Questions About the Fed Rate Hike
If you have a fixed-rate mortgage, your payments will not change. However, if you have an adjustable-rate mortgage (ARM), your monthly payments will likely increase when your rate adjusts according to your loan terms. Review your mortgage documents to understand your specific adjustment schedule and rate caps.
Refinancing becomes less attractive as interest rates rise. However, if you have an ARM, refinancing to a fixed-rate mortgage could provide payment stability, even if the new fixed rate is higher than your initial ARM rate. Consult a mortgage professional to evaluate if it makes financial sense for your situation, considering closing costs.
Higher interest rates generally lead to decreased homebuyer affordability and demand. This can result in a cooling of the housing market, potentially slowing down home price appreciation or even leading to modest price corrections in some areas. The overall effect depends on local market conditions and the magnitude of future rate increases.
The Federal Reserve’s future decisions are data-dependent, primarily influenced by inflation and employment figures. While the current hike suggests a continued effort to combat inflation, the pace and frequency of future increases are uncertain. Economists generally anticipate a few more modest hikes before a potential pause, but this can change with economic developments.
Homeowners can prepare by reviewing their finances, creating a detailed budget, and building an emergency fund. For ARM holders, consider making extra principal payments or exploring options to convert to a fixed-rate mortgage. Staying informed about economic news and consulting with financial advisors are also prudent steps.
Conclusion
The Federal Reserve’s recent 0.25% interest rate hike represents a pivotal moment for millions of homeowners across the United States. While fixed-rate mortgage holders may not feel an immediate pinch, those with adjustable-rate mortgages will likely see increased monthly payments, necessitating careful budget adjustments. Beyond individual finances, this move significantly influences the broader housing market, potentially moderating home price growth and shifting dynamics for both buyers and sellers. As the economic landscape continues to evolve, understanding these changes and adopting proactive financial strategies will be crucial for navigating the implications of this major shift in monetary policy and securing long-term financial stability. Staying informed about future economic indicators and consulting with financial professionals remains paramount for all stakeholders in the housing sector.