Student Loan Repayment 2026: 4 Critical Programs Explored
Anúncios
Effectively navigating student loan repayment in 2026 requires understanding key programs like Income-Driven Repayment (IDR) plans, Public Service Loan Forgiveness (PSLF), and other crucial options to manage educational debt.
As we look towards 2026, understanding how to manage educational debt becomes paramount for millions of Americans. The landscape of student finance is constantly evolving, making effective student loan repayment in 2026 a complex yet conquerable challenge. This article delves into the four most critical programs designed to assist borrowers, offering clarity and actionable insights.
Anúncios
The evolving landscape of student loan repayment
The journey through student loan repayment has never been a straight line, and in 2026, it continues to present new nuances. Economic shifts, legislative changes, and policy adjustments consistently reshape the options available to borrowers. Staying informed is not just beneficial; it’s essential for financial well-being.
Understanding the current environment involves recognizing how past changes, such as the COVID-19 payment pauses and subsequent policy adjustments, have set the stage for the coming years. Many borrowers are still adapting to the resumption of payments, and new programs are emerging to offer more tailored support. This section explores the broader context before diving into specific programs.
Anúncios
Why 2026 is a pivotal year for borrowers
- Policy Stabilization: After a period of significant flux, 2026 is anticipated to be a year where repayment policies become more stable, allowing borrowers to plan long-term.
- Economic Factors: Inflation rates and interest rate trends will continue to influence disposable income and the perceived burden of student debt.
- Program Awareness: Increased efforts are being made to educate borrowers about available programs, but individual responsibility for understanding options remains high.
The choices made today regarding repayment strategies will have lasting impacts on financial health. It’s crucial for borrowers to proactively engage with their loan servicers and utilize government resources to make informed decisions. The goal is not just to repay, but to repay smartly, minimizing stress and maximizing financial freedom.
Income-driven repayment (IDR) plans: a safety net for many
Income-Driven Repayment (IDR) plans are often the first line of defense for borrowers struggling with high monthly payments relative to their income. These plans adjust your monthly payment based on your discretionary income and family size, potentially reducing it to as low as $0 per month. The allure of IDR plans lies in their flexibility and the promise of loan forgiveness after a certain period, typically 20 or 25 years, depending on the specific plan.
In 2026, IDR plans remain a cornerstone of federal student loan repayment. The recent introduction of new IDR options and modifications to existing ones mean that borrowers have more choices than ever. However, navigating these options requires a clear understanding of each plan’s nuances, including how discretionary income is calculated, the length of the repayment term, and the tax implications of forgiveness.
Understanding the SAVE plan and its impact
The Saving on a Valuable Education (SAVE) Plan, launched in 2023, is a significant enhancement to the IDR landscape. It offers the lowest monthly payments of any IDR plan for many borrowers by increasing the amount of income protected from repayment calculations and eliminating interest capitalization in certain scenarios. This plan is particularly beneficial for those with lower incomes and larger loan balances.
- Lower Monthly Payments: Calculates payments based on a smaller portion of discretionary income compared to other IDR plans.
- Interest Benefit: Prevents unpaid monthly interest from capitalizing, meaning your loan balance won’t grow as long as you make your reduced payments.
- Faster Forgiveness: Some borrowers may qualify for forgiveness in as little as 10 years, depending on their original loan amount.
The SAVE plan represents a crucial evolution in IDR, aiming to make repayment more manageable and accessible. Borrowers currently on other IDR plans should evaluate if switching to SAVE would be more advantageous, as it could significantly reduce their financial burden and accelerate their path to forgiveness.
Public service loan forgiveness (PSLF): rewarding public servants
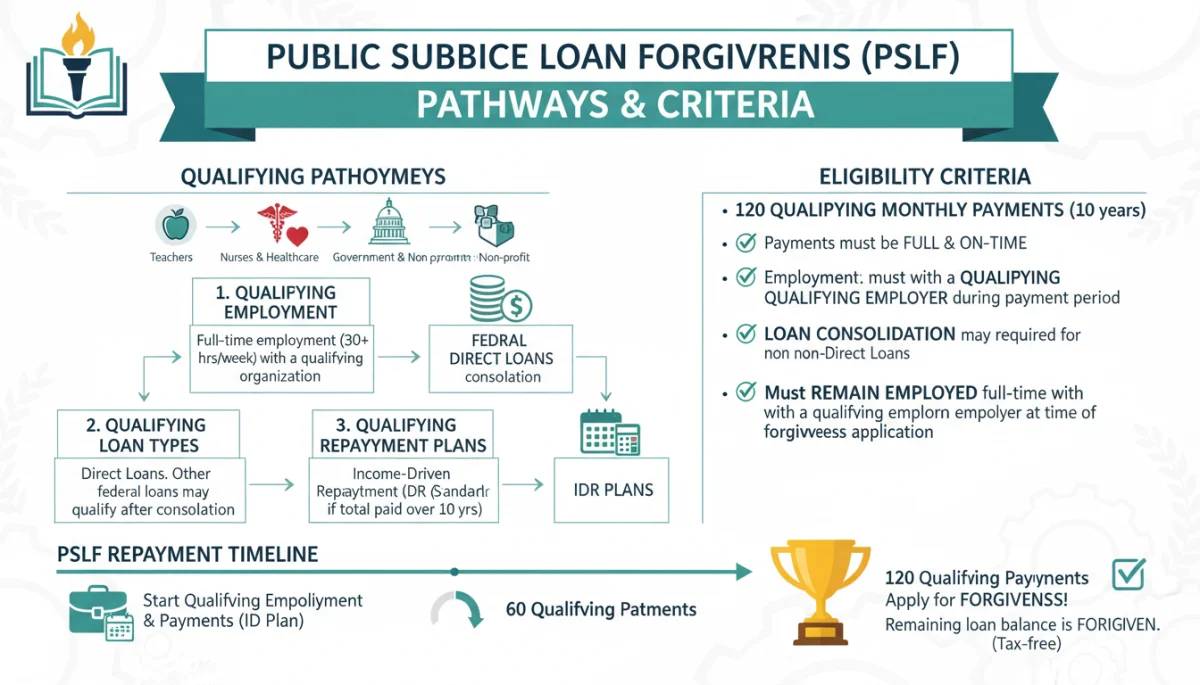
For those dedicated to public service, the Public Service Loan Forgiveness (PSLF) program offers a powerful incentive: the complete forgiveness of remaining federal student loan balances after 120 qualifying monthly payments. This program is specifically designed to encourage and reward individuals who work in government, non-profit organizations, or other qualifying public service roles. While initially complex, recent reforms have made PSLF more accessible and transparent, particularly for those who previously encountered difficulties.
In 2026, PSLF continues to be a vital pathway for many professionals. The key to successful PSLF pursuit lies in diligent tracking of employment and payments, ensuring all requirements are met. Understanding what constitutes qualifying employment and eligible loans is paramount, as mistakes can delay or even jeopardize forgiveness. The Department of Education has made strides in simplifying the application process and providing clearer guidance.
Eligibility and common pitfalls to avoid
To qualify for PSLF, borrowers must:
- Be employed full-time by a U.S. federal, state, local, or tribal government organization or a not-for-profit organization.
- Have Direct Loans or consolidate other federal loans into a Direct Consolidation Loan.
- Repay their loans under an income-driven repayment plan.
- Make 120 qualifying monthly payments.
Common pitfalls include not being on an IDR plan, having non-qualifying loans, or not submitting the Employment Certification Form annually. Regular communication with your loan servicer and utilizing the PSLF Help Tool are crucial steps to stay on track. The program’s stringent requirements necessitate careful attention to detail, but the reward of tax-free loan forgiveness is substantial for eligible individuals.
The strategic importance of PSLF cannot be overstated for those committed to public service. It transforms what might otherwise be a decades-long financial burden into a manageable path toward debt freedom, allowing professionals to focus on their impactful work without the overwhelming weight of student loans.
Loan consolidation and refinancing: optimizing your debt structure
Beyond federal repayment plans, borrowers often consider loan consolidation and refinancing as tools to optimize their debt structure. While often used interchangeably, these terms refer to distinct processes with different implications. Federal loan consolidation combines multiple federal loans into a single Direct Consolidation Loan, simplifying payments and potentially unlocking eligibility for certain federal programs. Refinancing, on the other hand, involves taking out a new loan, typically from a private lender, to pay off existing student loans, often with the goal of securing a lower interest rate.
In 2026, both options remain relevant, but the choice between them depends heavily on individual financial circumstances and goals. Federal consolidation is generally recommended if you want to maintain access to federal benefits like IDR plans and PSLF. Private refinancing might be attractive if you have excellent credit, a stable income, and are willing to forgo federal protections for a potentially lower interest rate or different repayment terms.
Federal consolidation vs. private refinancing
The decision to consolidate or refinance should be made with careful consideration of its long-term effects. Federal consolidation can extend your repayment period, potentially lowering monthly payments, but it might also increase the total interest paid over time. It’s an excellent option for simplifying payments and becoming eligible for IDR or PSLF if you weren’t already.
- Federal Consolidation Benefits:
- Simplifies multiple federal loans into one.
- Maintains eligibility for federal benefits (IDR, PSLF, deferment, forbearance).
- May lower monthly payments by extending the repayment term.
- Private Refinancing Benefits:
- Potentially lower interest rates, especially for borrowers with strong credit.
- Can reduce the total cost of the loan over its lifetime.
- Offers more flexible repayment terms, depending on the lender.
However, private refinancing means losing access to federal protections, which can be a significant risk if your financial situation changes unexpectedly. It’s crucial to weigh the benefits of a lower interest rate against the security of federal programs. For many, a hybrid approach—consolidating federal loans and then refinancing private loans separately—might be the most strategic choice.
Understanding deferment and forbearance: temporary relief options
Life is unpredictable, and sometimes borrowers face financial hardships that make consistent student loan payments impossible. In such situations, deferment and forbearance offer temporary relief by allowing you to pause or reduce your payments. While both options provide a temporary reprieve, they differ significantly in their criteria, impact on interest accrual, and duration. Understanding these distinctions is crucial for making an informed decision that doesn’t inadvertently worsen your financial situation.
By 2026, these options continue to serve as important safety valves for borrowers experiencing unemployment, economic hardship, or other qualifying circumstances. However, they should be used judiciously, as interest often accrues during these periods, potentially increasing the total amount you owe. Knowing when and how to apply for deferment or forbearance, and understanding their long-term implications, is a key component of effective loan management.
Key differences and strategic use
Deferment: This option allows you to temporarily postpone your loan payments. For certain types of federal loans (subsidized loans, Perkins loans, and the subsidized portion of consolidation loans), the government pays the interest that accrues during deferment, meaning your loan balance won’t grow. Common reasons for deferment include:
- Enrolling in school at least half-time.
- Unemployment or economic hardship.
- Active military duty.
Forbearance: With forbearance, your loan payments are also temporarily postponed or reduced. However, interest typically accrues on all types of federal loans during forbearance, and this accrued interest may be capitalized (added to your principal balance) at the end of the forbearance period. Forbearance is generally easier to obtain than deferment and is often granted for reasons such as:
- Financial hardship.
- Illness.
- Participation in a medical residency or dental internship.
Strategic use of deferment or forbearance involves careful planning. While they offer immediate relief, they are not long-term solutions. It’s often advisable to explore income-driven repayment plans first, as they offer lower payments while keeping you on track for potential loan forgiveness, without the same interest accrual risks as forbearance. If deferment is an option and interest won’t accrue, it can be a more favorable choice for temporary relief.
Navigating default and delinquency: prevention and recovery
Falling behind on student loan payments can lead to delinquency, and eventually, default. These situations carry severe consequences, impacting your credit score, eligibility for future federal aid, and potentially leading to wage garnishment or tax refund offset. Preventing default is always the best strategy, but if you find yourself in a precarious position, understanding the steps to recovery is crucial. The federal government offers various pathways to bring defaulted loans back into good standing, and being proactive can mitigate the damage.
In 2026, the emphasis remains on borrower education and accessible solutions to prevent and resolve default. The Fresh Start program, for instance, has provided a critical opportunity for millions of defaulted federal student loan borrowers to re-enter repayment in good standing. This initiative underscores the government’s commitment to helping borrowers avoid the most severe repercussions of default, offering a second chance to manage their debt responsibly.
Understanding the fresh start program and rehabilitation
The Fresh Start program, a temporary initiative, has allowed eligible defaulted federal student loan borrowers to regain good standing by simply contacting their loan servicer. Benefits include:
- Removal of the default status from credit reports.
- Eligibility for federal student aid.
- Access to income-driven repayment plans.
For those who miss the Fresh Start window or have other types of defaulted loans, loan rehabilitation remains a primary method for recovery. Rehabilitation involves making nine voluntary, reasonable, and affordable monthly payments within 10 consecutive months. Upon successful completion:
- The default record is removed from your credit report (though the delinquency remains).
- You regain eligibility for federal student aid.
- You can choose an income-driven repayment plan.
Another option, loan consolidation, can also get a defaulted loan out of default if you agree to repay the new Direct Consolidation Loan under an income-driven repayment plan or make three consecutive, on-time payments on the defaulted loan before consolidating. Regardless of the path, acting quickly and communicating with your loan servicer are the most important steps to take when facing delinquency or default.
Resources and tools for informed decision-making
Successfully navigating student loan repayment in 2026 doesn’t have to be a solitary endeavor. A wealth of resources and tools are available to help borrowers understand their options, manage their accounts, and make informed decisions. Leveraging these resources can significantly reduce the complexity and stress associated with student debt, providing clarity and support throughout your repayment journey. From government websites to non-profit counseling services, assistance is readily accessible for those who seek it.
The digital age has made financial information more available than ever, but it also necessitates discerning reliable sources from misleading ones. Focusing on official government channels and reputable non-profit organizations ensures you receive accurate and up-to-date guidance. These resources are designed to empower borrowers, offering personalized advice and practical tools to optimize repayment strategies.
Key resources to utilize
Several essential resources can guide you through the intricacies of student loan repayment:
- Federal Student Aid (StudentAid.gov): This is the official website for federal student aid, offering comprehensive information on all federal loan programs, repayment options, and application forms. It’s the primary source for accurate and up-to-date federal student loan information.
- Your Loan Servicer’s Website: Your loan servicer is your direct point of contact for managing your loans, making payments, and applying for specific repayment plans or relief options. Their website will have account-specific information and tools.
- Non-Profit Credit Counseling Agencies: Organizations like the National Foundation for Credit Counseling (NFCC) offer free or low-cost counseling services, providing personalized advice on budgeting, debt management, and student loan strategies.
- Online Calculators and Tools: Many websites offer student loan calculators that can help you compare repayment plans, estimate monthly payments, and project total interest paid over time.
Proactively engaging with these resources can transform a daunting task into a manageable process. Regular checks on your loan status, understanding policy updates, and seeking expert advice when needed are practices that will pay dividends in your financial future. Remember, the goal is to not just repay your loans, but to do so in the most financially advantageous way possible.
| Program | Key Benefit |
|---|---|
| Income-Driven Repayment (IDR) | Adjusts monthly payments based on income and family size, with potential forgiveness after 20-25 years. |
| Public Service Loan Forgiveness (PSLF) | Forgives remaining federal loan balance after 120 qualifying payments for public service workers. |
| Loan Consolidation | Combines multiple federal loans into one, simplifying payments and potentially unlocking new benefits. |
| Deferment & Forbearance | Provides temporary payment relief during financial hardship, with varying impacts on interest accrual. |
Frequently asked questions about student loan repayment
Federal loan consolidation combines existing federal loans into a new federal loan, retaining federal benefits. Private refinancing involves taking a new loan from a private lender to pay off existing loans, potentially lowering interest but sacrificing federal protections.
PSLF is for borrowers employed full-time by a U.S. federal, state, local, or tribal government organization or a qualifying non-profit. They must have Direct Loans, be on an IDR plan, and make 120 qualifying payments.
The SAVE plan offers the lowest monthly payments for many, by protecting more income from discretionary calculations and preventing interest capitalization as long as payments are made. It aims to make repayment more affordable and prevent balances from growing.
While offering temporary relief, these options often lead to interest accrual, potentially increasing your total loan balance over time. Forbearance, especially, can result in capitalized interest, adding to your principal balance once the period ends.
If your federal student loans are in default, you can explore options like loan rehabilitation, consolidation, or, if available, the Fresh Start program. These pathways aim to bring your loans back into good standing and restore eligibility for federal benefits.
Conclusion
Successfully navigating student loan repayment in 2026 requires a proactive approach and a thorough understanding of the available programs. From the flexible relief offered by Income-Driven Repayment plans, including the beneficial SAVE plan, to the transformative potential of Public Service Loan Forgiveness, borrowers have several powerful tools at their disposal. Additionally, strategic decisions regarding loan consolidation or private refinancing, alongside judicious use of temporary relief options like deferment and forbearance, can significantly impact financial well-being. Preventing default through awareness and utilizing accessible resources are key to managing student debt effectively and paving the way for a more secure financial future. It is imperative for borrowers to stay informed, engage with their loan servicers, and explore every avenue to optimize their repayment strategy.